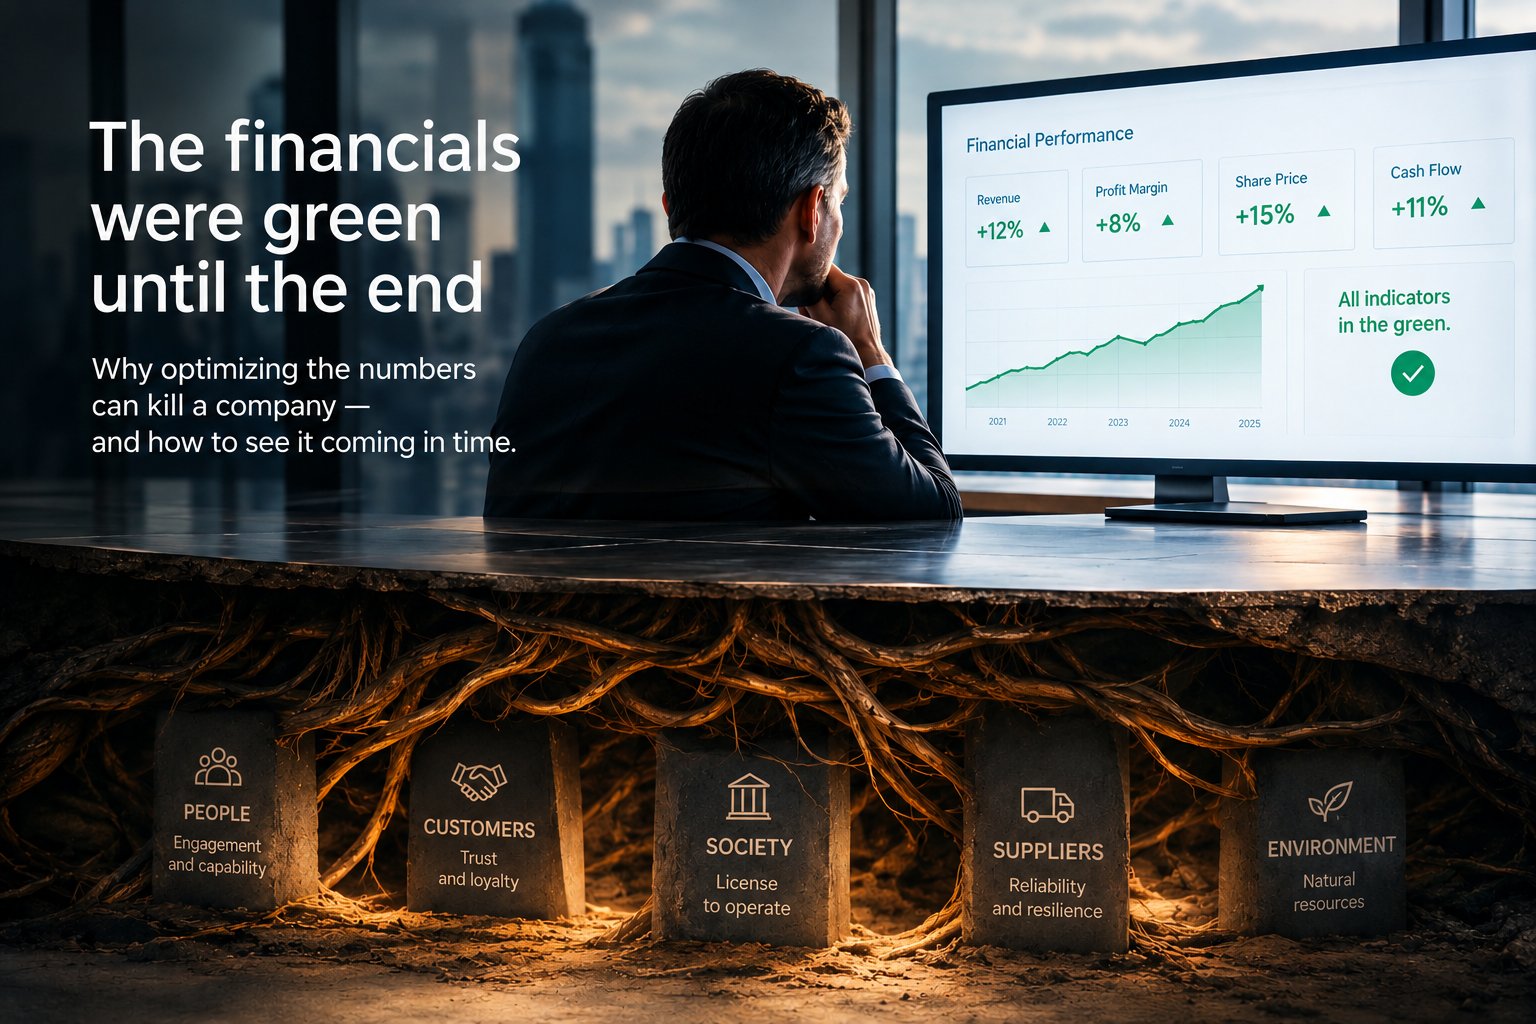
Why optimizing the numbers can kill a company — and how to see it coming in time. Wim Van Laere · Integration Capacity Analysis · October 2026
In 2005, researchers asked 401 chief financial officers a simple question. Would you sacrifice long-term value to deliver a smooth quarter? Seventy-eight percent said yes. Eighty percent said they would cut research, advertising or maintenance to hit a target they themselves called arbitrary.
So the people letting the financial numbers run the show know they are extracting. They know the trade is bad, and still they make it, year after year. That is neither strategy nor execution. It is the very definition of a spell: harm that stays invisible long enough to feel like success. Walk into any corporate boardroom obsessed with quarterly earnings and share price, and you will see the spell at work.
Every company runs on bonds. The bond with the people who do the work. The bond with customers. The bond with suppliers. The bond with society. The bond with the environment. All value flows through these bonds. Their strength, their thickness, their coherence, their orientation — that is the real story of an organization. Still, in the books they appear only as costs. The cost of every bond is measured. The state of every bond is a guess.
When the only visible side of a bond is its cost, squeezing it always looks like improvement. A little less quality in the product, or lowering safety standards. A little more filler, or less product for the same price. Cheaper customer service. Subscription traps. One more task on the same people. Stagnating benefits. Each squeeze books a gain immediately. The long-term damage books nothing, anywhere. And since nothing visible happens, the lesson drawn is that it was fine — so next quarter goes one step further. This is how bonds hollow out: not through one big betrayal, but through a thousand small improvements, each one defensible, each one booked as progress.
That is the entire spell. Not evil people. An instrument panel that shows the gain of every squeeze and the cost of none.
The spell is not a law of nature, and it was cast in two stages. In 1970, Milton Friedman gave the permission: the only social responsibility of business is profit. The spell was perfected through agency theory, buybacks legalized in 1982, and executives paid in stock. The target quietly moved further, from maximizing company profit to maximizing shareholder return. That shift is bigger than it sounds: profit is a result of the business; shareholder return is the market’s expectation about how much money can be extracted from a business. Since then, leaders are rewarded less for managing the company than for managing the story about the company.
In fairness, the share price is not blind. Investors do pay for trust and brand strength; part of every share price rests on them. But an investor can only judge from what a company publishes, and no company publishes the condition of its bonds. So a company can hollow out its customer trust for ten years, and in its reports those are ten good years. The day the damage becomes undeniable, it enters the books all at once, as a write-down or a profit warning. By then the managers who did the squeezing have usually collected their bonuses and moved on. And the manager who refused to squeeze? She showed weaker numbers than her competitors every quarter along the way. This is why no villains are needed. A system that shows the gains immediately and hides the damage for years pushes everyone in the same direction — decent people included.
Many have tried to fix this. Stakeholder capitalism, the balanced scorecard, the triple bottom line, ESG — in 2019, 181 CEOs of the Business Roundtable solemnly redeclared what companies are for, and research later showed the signatories changed nothing. Every attempt failed the same way: it changed what companies declare, while the rewards stayed wired to the share price. One more report on top of the dashboard. Never a way to see what the dashboard misses.
General Electric fell from the world’s most valuable company to a breakup; Jack Welch, who built it, admitted that shareholder value “is a result, not a strategy” and that treating it as the strategy was “the dumbest idea in the world.” Boeing spent $43 billion on buybacks while its engineers lost the argument, and has not made an annual profit since 2018. Intel paid out more than its entire net income and lost the technology lead it had held for fifty years.
In every case, the years before the fall were record years. Boeing in 2018 was, by every number it watched, the healthiest it had ever been. The indicator being optimized is always the last to turn red, because it is the thing being managed.
The same erosion runs inside the organization. Where contribution is invisible and visibility is rewarded, employees draw the rational conclusion: promote yourself. Eighty-three percent now admit to performative work; nearly half spend a day a week performing their work instead of doing it. Everyone acts sensibly. The whole comes apart. And the top floor is the last to feel it: 85 percent of executives say they live their purpose at work. Among the people who do the daily work, 15 percent say the same.
The opposite exists. Some fifty companies in Europe are older than two hundred years; Japan counts thirty-three thousand older than a century. Nearly all are family-held, reinvest where others extract, and treat their bonds — with workers, customers, place — as the asset everything else grows from. Their names are unknown for the best reason: nothing ever happened to them. The pattern is not only old. Companies whose own employees rate them the best places to work have beaten the market by two to four percent a year for thirty-five years. Thick bonds are not charity. They are the longest-performing asset on record.
A spell built on not-seeing breaks the moment you see. The conditions that broke GE and Boeing never reached their dashboards, but they were in their documents all along — readable, years early, by anyone who knew what to look for. They still are.
That is what a Structural Reading does. From an organization’s own records and conduct — no surveys, no self-reports — it reads:
A few weeks of reading. One report a board can act on. A Structural Reading is most valuable before consequential action — a transformation, an acquisition, a restructuring, a major investment — when the question is not whether the plan is right, but whether the organization can carry it.
The spell of sacrificing long-term value for short-term numbers is not limited to business. It also runs through governments and through our local and global institutions, and the damage to the bonds of civilization becomes clearer year by year. A perception is spreading that collapse can no longer be averted — that our institutions are the causes, not the solutions. I disagree. The institutions themselves are not the cause; their orientation is.
David Graeber described bullshit jobs: work that serves no one, and that the people doing it cannot justify to themselves. The same test works at every scale. A company that no longer strengthens a single bond it depends on is a bullshit company, whatever its revenue. A government that no longer strengthens the bonds it was created to protect is a bullshit government, whatever its activity. The test is not cynicism — it is responsibility, distributed: companies owe the societies that carry them real value; governments owe those same societies direction. Despair is just the spell’s last trick: it tells you the damage can neither be seen nor repaired. Both are false. The way back is reorientation — and no one has to wait for anyone else to start. A company cannot rebind a society on its own. But it can rebind itself, and its own bond to society, and that is where every larger repair begins.
One sentence for your next board meeting: our growth figures tell us what we extracted — they do not tell us what we consumed. If you want to know, it can be read.
Every number in this piece is sourced; the evidence file is available on request.
Wim Van Laere — Integration Capacity Analysis · wim@integrationcapacity.org · integrationcapacity.org